Indian Institute of Technology Madras
BS Degree Programme · Examination & Study Paper
Machine Learning Practice
Text, image & time-series data
Official Paper
Examination Instructions & Guidelines
- Solve on notebook/paper first before checking solutions.
- MCQ: Exactly 1 option is correct. Negative marking applies.
- NAT: Numerical response. No negative marking.
- Scientific calculator allowed for all calculations.
- Official answer key is sealed at the end of this sheet.
End Term · 31 Aug 2025 (FN)End Term
- Q1MCQ2 Marks·Choose one option
What is the primary function of the pandas.resample() method for a time series?
- ATo convert a DataFrame to a series or vice versa.
- BTo fill in missing values in the time series using various interpolation methods.
- CTo change the frequency of the time series, such as converting daily data to monthly or monthly data to daily.
- DTo perform statistical tests to check for stationarity in the time series.
- Q2MCQ3 Marks·Choose one option
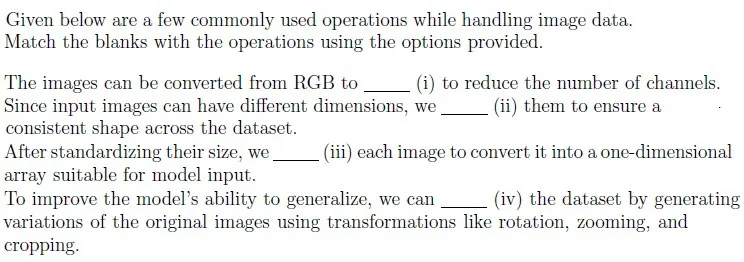
- A(i) – resize, (ii) – augment, (iii) – flatten, (iv) – grayscale
- B(i) – grayscale, (ii) – flatten, (iii) – resize, (iv) – augment
- C(i) – grayscale, (ii) – augment, (iii) – resize, (iv) – flatten
- D(i) – grayscale, (ii) – resize, (iii) – flatten, (iv) – augment
- Q3MCQ3 Marks·Choose one option
A time series with a clear upward trend and increasing variance over time is identified as non- stationary. Which two preprocessing steps are most likely required?
- AMin-Max scaling and seasonal decomposition
- BImputing missing values and differencing
- CLog transformation and differencing
- DStandardization and moving average smoothing
- Q4NAT2 Marks·Write the number
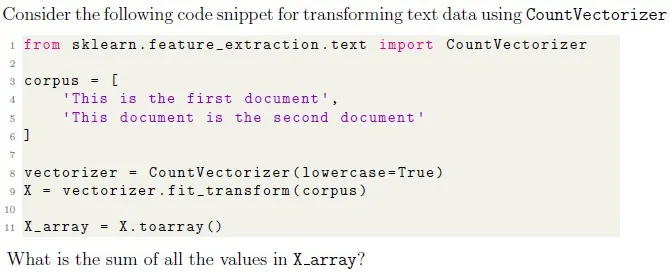 Your answer:
End Term · 31 Aug 2025 (AN)End Term
- Q5MCQ2 Marks·Choose one option
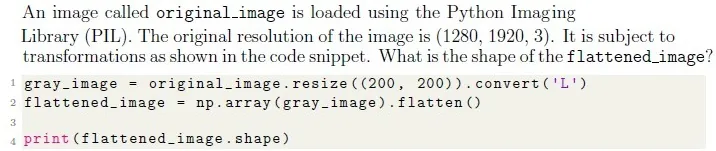
- A(200, 200, 3)
- B(40000, )
- C(200, 200, 1)
- D(40000, 3)
- Q6MCQ2 Marks·Choose one option
Which of the following statements about the Augmented Dickey-Fuller (ADF) test is correct?
- AThe test is used to detect seasonality in a time series
- BA low p-value (e.g., < 0.05) indicates the time series is non-stationary
- CThe test’s null hypothesis is that the time series is stationary
- DA low p-value (e.g., < 0.05) indicates the time series is stationary
- Q7MCQ3 Marks·Choose one option
Which of the following best describes the components of a time series in a classical multiplicative decomposition model?
- AThe series is a product of a trend component and an error component only
- BThe series is a sum of a trend component, a seasonal component, and a cyclical component
- CThe series is a product of a trend component, a seasonal component, and an error component
- DThe series is a sum of a trend component, a seasonal component, and a error component
- Q8NAT3 Marks·Write the number
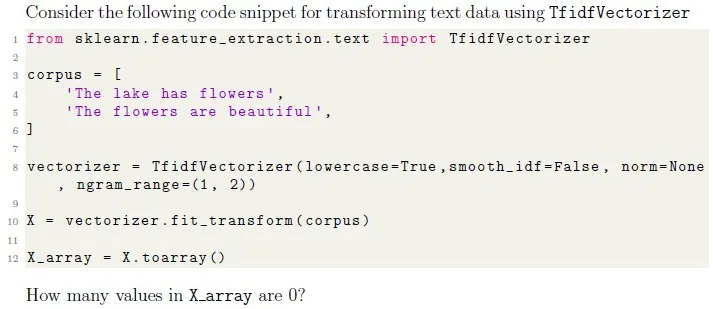 Your answer: